
John Marra,
Timberlake Mayor
October 13, 2026
Willoughby-Eastlake Schools Want More Money
Taxpayers Should Demand More Accountability
By John Marra, Mayor of Timberlake | October 13, 2026
Willoughby-Eastlake Schools want voters to approve a 0.75% earned-income tax this November, projected to raise approximately $14 million annually: $9.6 million for operations and $4.45 million for permanent improvements. The tax would continue without an automatic expiration date. Before approving it, taxpayers deserve more than warnings about cuts. They deserve proof that the district has exhausted reasonable efficiencies.
A resident earning $50,000 would pay another $375 a year; at $100,000, $750. Working seniors with taxable earnings would also pay. For families struggling with groceries, utilities, childcare and housing, that money matters.
Meanwhile, federal enrollment figures show 8,211 students in 2014 compared with 6,861 in 2024–25—a decline of 1,350, or 16.4%. More recent district figures suggest approximately 6,300–6,400 students. Why should operating costs keep rising without a transparent explanation of how staffing and facilities have adjusted to substantially fewer children?
The district reports approximately 989 employees; federal records list 949.25 full-time-equivalent staff for 2024–25. Headcounts and full-time equivalents are not interchangeable, and hose figures do not establish that staffing increased. But they make a decade-long, apples-to- apples accounting essential. Have positions, payroll and benefits declined as enrollment fell—or has spending per student continued to rise?
Ohio’s FY2025 Cupp Report identifies 48 administrator full-time equivalents at Willoughby- Eastlake Schools, with an average annual salary of $107,960—approximately $5.18 million in administrative salaries before benefits. This is substantially higher than the 27 administrator FTEs identified under a different federal reporting classification. Taxpayers deserve to know exactly which positions are included, how many principals, assistant principals, directors, supervisors and coordinators the district employs, and how those numbers and their total compensation have changed as enrollment declined.
Teacher assignments, including tenured positions, should also be evaluated against enrollment, class sizes and student needs. That is not a call for indiscriminate layoffs. It is basic fiscal oversight.
And who pays this new tax? A conventional property-tax levy reaches taxable residential, commercial and industrial property. This proposal instead taxes qualifying earned income and net self-employment earnings of district residents. A company may own valuable commercial property and employ hundreds locally, yet its property bears none of this particular increase. Employees living in the district pay; employees who work here but live elsewhere generally do not. Businesses retain their existing property-tax obligations, but do not share in this new increase through their property. The next burden lands on resident paychecks.
Ohio lawmakers helped create this predicament. House Bill 920 limits revenue growth from many existing voted property-tax levies. In DeRolph v. State, the Ohio Supreme Court found Ohio’s school-funding system unconstitutional. That decision neither outlawed property taxes nor required full state funding, but it reinforces the case for serious statewide reform—not simply shifting more pressure onto working residents.
The district says the tax would help maintain two high schools, programs, career-technical opportunities and facilities. Skilled-trades education is valuable, but programs must demonstrate participation, outcomes and costs. Taxpayers also deserve actual trends in reading, mathematics and other academic results—not just promises of expanded offerings.
Facilities require equal scrutiny. Schools, stadiums, tracks and other amenities carry ongoing staffing, utility, maintenance and replacement expenses even as enrollment shrinks. Consolidation is not automatically a failure; it may be responsible stewardship.
The district warns that defeat could bring high-school and middle-school consolidation, other building changes and staffing reductions beginning in 2028–29. Publicly circulated statements raise a further question: could consolidation remain under consideration even if the tax passes? Those statements must be verified against official district records. The board should answer plainly and publish building-by-building operating costs, utilization, savings and timelines for both election outcomes.
Before asking for a permanent tax, publish a ten-year comparison of enrollment, staffing, total compensation, inflation-adjusted spending per student and academic
achievement—plus a written efficiency and consolidation plan. Taxpayers should not have to approve the tax first and see the analysis afterward.
This is not opposition to students, teachers or public education. It is a demand that the board justify its decisions and that lawmakers confront an inequitable funding system. Accountability before taxation. Efficiency before expansion. Fairness before shifting another burden onto working families.
ADVERTISEMENTS
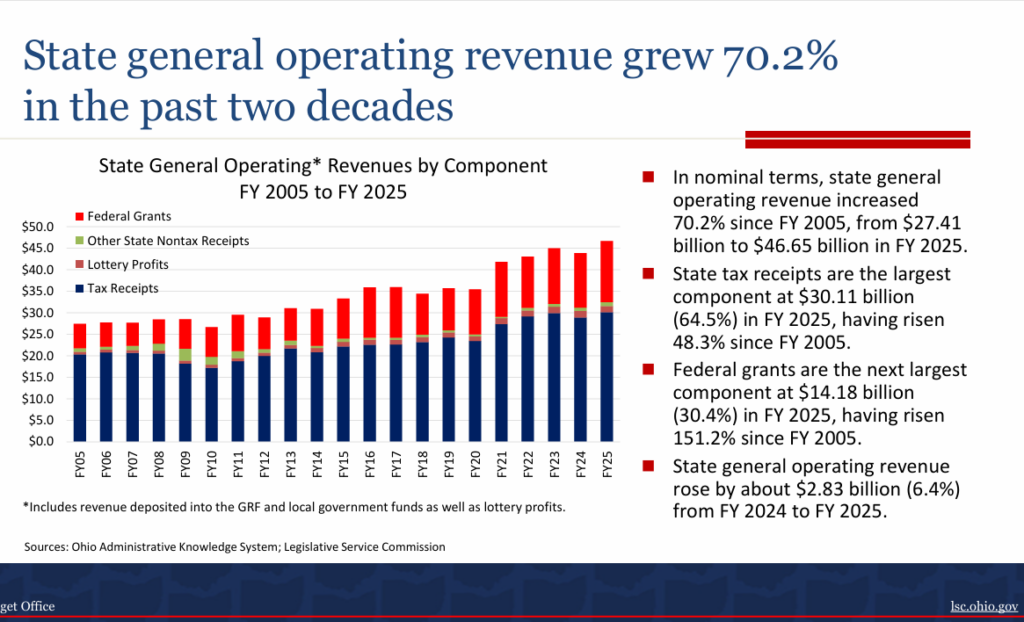
We do not have a problem generating revenue in this state, we have a spending problem
Categories: Community Activism, Education, Lake County - General